Buying a home is one of the biggest financial decisions most people will ever make. Yet many buyers begin the process having assumptions that may be outdated, incomplete, or simply wrong.
You may have heard that you need 20% down, or that you need perfect credit, or that getting preapproved will hurt your credit score. Maybe you believe FHA loans are only for first-time buyers or that renting is always cheaper than owning.
These mortgage myths can do more than create confusion. They can cause qualified buyers to delay purchasing, overlook loan programs they may qualify for, or put more money down than they need.
The reality is that mortgage qualification depends on your individual financial situation, the property you are buying, the loan program, your income, credit history, debts, assets, and other factors.
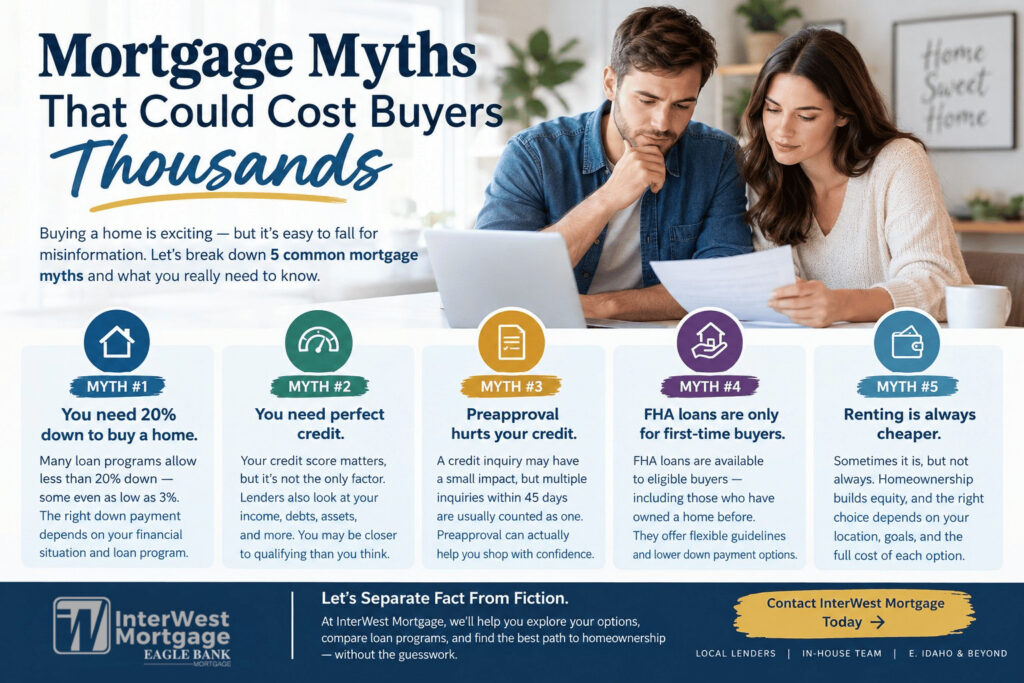
Here are five of the biggest mortgage myths—and what home buyers should know instead.
Myth #1: You Need 20% Down to Buy a Home
This may be one of the most persistent homebuying myths.
You do not necessarily need 20% down to buy a home.
The Consumer Financial Protection Bureau says the required down payment amount varies by loan program and lender. Some mortgage programs allow significantly smaller down payments, while others allow eligible borrowers to purchase with no down payment.
Freddie Mac notes that down payments can be as low as 3% with some conventional mortgage programs. FHA financing can require as little as 3.5% for eligible borrowers.
Why Do People Think 20% Is Required?
There is a reason this number comes up so often.
With many conventional mortgages, putting less than 20% down can mean paying private mortgage insurance, or PMI. PMI protects the lender against certain losses if the borrower fails to repay the loan. It does not mean that a buyer cannot qualify with less than 20% down.
A larger down payment can also reduce the amount borrowed and potentially lower the overall cost of the mortgage.
But that does not automatically make 20% the right amount for every buyer.
Consider a buyer with $60,000 saved. Putting $60,000 toward a home could leave very little money available for closing costs, moving expenses, repairs, emergencies, or other financial needs.
The CFPB recommends considering these other expenses when determining how much cash to set aside for a home purchase.
What Buyers Should Ask Instead
Instead of asking:
“Do I have enough money for 20% down?”
Ask:
“What down payment makes sense for my financial situation and the loan programs I may qualify for?”
That is a much more useful question.
In fact, the National Association of REALTORS® reported that the median down payment for first-time buyers was 10% in 2025, while repeat buyers had a median down payment of 23%.
A mortgage professional can help you compare different down payment scenarios and see how each one could affect your monthly payment, mortgage insurance, cash needed at closing, and overall loan cost.
Myth #2: You Need Perfect Credit to Get a Mortgage
Another common misconception is that you need a nearly perfect credit score before a lender will consider you for a mortgage.
That’s not how mortgage lending works.
Your credit profile is important, but mortgage qualification is based on more than one number.
Lenders may consider your credit history, income, employment, debts, assets, down payment, loan type, and other factors when evaluating your application.
FHA loans are one example of a program designed with different credit qualifications than conventional financing. HUD says FHA-insured mortgages have a lower minimum credit score requirement than most conventional mortgages, although individual lender requirements and other underwriting factors still apply.
A Lower Credit Score Doesn’t Necessarily Mean “No”
It may mean fewer options, different pricing, a different down payment requirement, or a need to address credit issues before purchasing.
But assuming that a less-than-perfect credit score automatically disqualifies you could prevent you from having a conversation that might reveal legitimate options.
And there is another reason to talk to a mortgage professional early.
You may be closer to qualifying than you think.
An experienced loan officer can review your situation and explain what is helping your application, what may be holding it back, and whether there are practical steps you can take before applying.
Don’t Try to Fix Your Credit in a Vacuum
If you’re planning to buy a home, be careful about taking out new credit cards, financing a vehicle, closing old accounts, or making other major financial changes without understanding how they could affect your mortgage application.
A lender can help you determine which moves may help—and which could create unnecessary complications.
Myth #3: Getting Preapproved Will Hurt Your Credit
This myth causes some buyers to avoid one of the most useful early steps in the homebuying process.
The truth is a little more nuanced.
A mortgage preapproval generally involves a credit inquiry, and a hard inquiry can have a small impact on your credit score. The CFPB confirms that lenders may obtain your credit report when determining how much they are willing to lend for a mortgage preapproval.
But that doesn’t mean you should avoid shopping for a mortgage.
The CFPB also explains that when consumers shop around for a mortgage, multiple mortgage credit checks within a 45-day window are generally recorded as a single inquiry for scoring purposes.
Why Preapproval Can Be Valuable
A preapproval can help you understand what you can realistically afford before you start seriously shopping for homes.
It can also help identify potential issues before you are under contract.
For example, a lender may discover that you need to document income differently, pay down certain debt, correct an error on your credit report, or provide additional documentation.
Finding those issues early is generally much easier than discovering them after you’ve made an offer on a home.
InterWest Mortgage encourages prospective buyers to begin the financing conversation early and provides online prequalification resources through its local loan officers.
Myth #4: FHA Loans Are Only for First-Time Home Buyers
FHA financing is often associated with first-time buyers—and for good reason.
FHA loans can offer lower down payment requirements and flexible qualification guidelines, which can make them useful for some buyers.
But FHA loans are not exclusively for first-time home buyers.
HUD’s current FHA guidance does not restrict FHA-insured purchase mortgages to first-time buyers. FHA financing can be available to eligible borrowers who have previously owned a home, provided they meet the applicable requirements.
That’s an important distinction.
FHA vs. Conventional: There Isn’t One Universal “Best” Loan
A buyer shouldn’t automatically choose FHA simply because it allows a lower down payment.
Likewise, a buyer shouldn’t automatically choose conventional financing simply because they have good credit.
The right comparison can involve:
- Down payment requirements
- Credit profile
- Monthly mortgage insurance
- Interest rate
- Closing costs
- Debt-to-income ratio
- Property type
- Cash reserves
- Long-term plans
- Overall cost of the loan
For some borrowers, conventional financing may make more sense. For others, FHA may provide a useful path to homeownership.
The key is comparing the actual numbers for your situation rather than choosing based on something you heard from a friend, saw on social media, or read years ago.
Myth #5: Renting Is Always Cheaper Than Buying
This one is especially important because there is a piece of truth behind it.
Sometimes renting is cheaper than buying.
But “renting is always cheaper” is not an accurate rule of thumb.
Housing costs vary dramatically by location, property, financing terms, taxes, insurance, maintenance, and how long someone plans to stay in the home.
Freddie Mac notes that renting can make sense for people who need flexibility, expect to move soon, or live in areas where renting is less expensive than buying. At the same time, buying can provide an opportunity to build equity and potentially benefit from future home price appreciation.
Current housing research also shows why this comparison needs to be individualized. Freddie Mac found in its 2024 analysis that mortgage payments on intended purchases were generally higher than applicants’ current rents.
At the same time, comparing rent and mortgage payments alone doesn’t tell the entire financial story.
Buying Has Costs That Renters Don’t Have
Homeowners are responsible for expenses such as:
- Property taxes
- Homeowners insurance
- Maintenance
- Repairs
- Utilities
- Mortgage interest
- Potential mortgage insurance
- Closing costs
The CFPB emphasizes that buyers need to consider the full monthly housing payment—not just principal and interest.
Harvard’s Joint Center for Housing Studies has also documented rising homeowner expenses, including insurance, property taxes, utilities, and routine maintenance.
But Renting Has Costs, Too
Renters don’t build home equity through their rent payments.
Rent can also increase over time, and renters may face security deposits, application fees, moving expenses, renters insurance, parking fees, and other costs depending on the property and lease.
Freddie Mac notes that rent increases are another cost renters need to really consider when planning for the long term. These increases can come yearly or when you update your rental agreement.
So the better question isn’t:
“Is renting cheaper?”
It’s:
“Which option makes the most financial sense for me, given my budget, goals, timeline, and local housing market?”
That is a question worth running the numbers on.
Other Mortgage Mistakes That Can Cost Buyers Money
The five myths above aren’t the only misconceptions that can affect a home purchase.
Assuming the Interest Rate Is the Only Number That Matters
A lower advertised rate doesn’t automatically mean a lower-cost mortgage.
Buyers should consider the entire loan structure, including points, fees, mortgage insurance, closing costs, and other terms.
The CFPB recommends comparing loan options based on overall costs and terms rather than focusing on a single number.
Forgetting About Closing Costs
Your down payment isn’t the only cash you’ll need.
Closing costs can include lender fees, title-related expenses, prepaid taxes and insurance, and other transaction costs. Freddie Mac notes that closing costs can add thousands of dollars to a purchase.
That’s why a good mortgage conversation should address cash needed to close, not simply the down payment.
Waiting Until You Find a House to Talk to a Lender
One of the most expensive mistakes can be shopping for homes before understanding your financing.
Knowing your potential price range, estimated monthly payment, cash requirements, and loan options can help you shop with a much clearer understanding of what you’re actually considering.
How InterWest Mortgage Can Help You Separate Mortgage Facts From Myths
Mortgage information is everywhere.
Friends have opinions. Family members have experiences. Social media has advice. Online mortgage calculators can provide estimates.
The problem is that none of those sources know your complete financial situation.
That’s where a conversation with an experienced mortgage professional can make a difference.
InterWest Mortgage has served Idaho Falls, Blackfoot, Shelley, Pocatello, Rigby, Rexburg, Driggs, Island Park, Victor, and Bonneville County since 1986 and operates with an in-house team, with its loan professionals and processing operations working under the same roof. The company serves buyers throughout Eastern Idaho.
Its current loan team includes Joni Kepler, Jason Speirs, and Sean Finch, whose combined mortgage experience exceeds 75 years.
That experience can be particularly valuable when your situation doesn’t fit neatly into the simple mortgage advice you see online.
Instead of asking:
“What does everyone have to do to buy a house?”
Ask:
“What mortgage options make the best sense for my situation?”
That conversation can help you understand your potential loan programs, down payment options, credit considerations, estimated monthly payment, closing costs, and other factors before you make a major financial commitment.
Don’t Let a Mortgage Myth Decide When You Buy
You may not need 20% down.
You may not need perfect credit.
A mortgage preapproval doesn’t mean your credit is permanently damaged.
FHA financing isn’t limited to first-time buyers.
And renting isn’t automatically cheaper than owning.
The bigger lesson is that there is rarely a one-size-fits-all answer in mortgage lending.
Your income, credit, savings, debts, goals, location, home price, loan program, and timeline all matter.
The best way to find out where you stand is to stop guessing and have a conversation with an experienced mortgage professional.
InterWest Mortgage can help you separate mortgage facts from myths, compare your available options, and understand what your next step could look like.
If you’re considering buying a home in Idaho Falls, Rexburg, Rigby, Shelley, Pocatello, Ammon, Blackfoot, Driggs, Island Park, Victor, or any of the surrounding Eastern Idaho communities, contact InterWest Mortgage to discuss your situation and explore your home financing options.
Don’t let an outdated mortgage myth keep you from finding out what’s actually possible. Give us a call at (208) 525-8778.