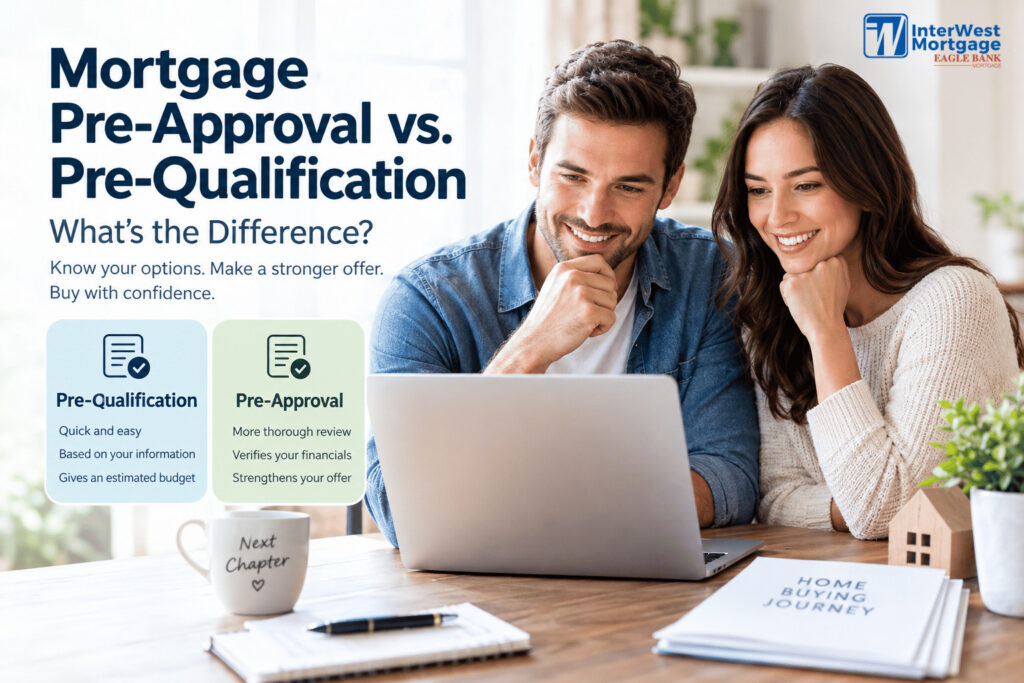
If you are thinking about buying a home, you have probably heard the terms mortgage pre-qualification and mortgage pre-approval. They sound almost identical, but there can be a meaningful difference when you are ready to make an offer.
A pre-qualification can be a useful first step when you are simply trying to understand how much home you can afford. A mortgage pre-approval, however, generally carries more weight when you are seriously shopping for a home and competing against other buyers.
But there is an important detail that many homebuyers—and even some sellers—get wrong: the words “pre-qualified” and “pre-approved” do not have a universal definition across lenders. The Consumer Financial Protection Bureau (CFPB) explains that lenders use these terms differently. Some lenders may issue a pre-qualification based primarily on information provided by the borrower, while others may use the term to refer to a more detailed review.
So, what really matters? How much of your financial information has actually been reviewed and verified?
For homebuyers in Idaho and beyond, understanding that distinction can help you shop more confidently, write stronger offers, and avoid unpleasant surprises later.
What Is Mortgage Pre-Qualification?
A mortgage pre-qualification is generally an early estimate of how much you may be able to borrow.
During a pre-qualification, you may provide information about your:
- Income
- Employment
- Monthly debts
- Assets and savings
- Estimated down payment
- Credit history
Depending on the lender, some or much of this information may be self-reported rather than fully documented and verified.
The lender uses the information to estimate your potential borrowing power and give you an idea of the price range you may want to consider.
When Is Pre-Qualification Useful?
Pre-qualification can be helpful if you are at the beginning of your homebuying journey and aren’t ready to make an offer yet.
For example, perhaps you are wondering:
“Can I afford a $350,000 home?”
or:
“Would I qualify for a $500,000 mortgage?”
A conversation with a mortgage professional can help you establish a preliminary budget before you begin seriously looking at homes.
However, a pre-qualification should generally be viewed as an estimate—not a guarantee of financing. Fannie Mae describes pre-qualification as an estimate of the amount a borrower may be able to borrow, with documentation generally required later in the process.
What Is Mortgage Pre-Approval?
A mortgage pre-approval is generally a more thorough evaluation of your financial situation.
Instead of relying primarily on information you provide verbally or through a basic form, the lender typically reviews documentation such as:
- Pay stubs
- W-2s
- Tax returns, when applicable
- Bank statements
- Employment information
- Outstanding debts
- Credit history
- Available funds for the down payment and closing costs
The lender uses this information to determine how much you may be qualified to borrow under the applicable loan program.
Freddie Mac notes that a pre-approval can help buyers understand their price range and demonstrate to sellers that they are serious about purchasing a home.
A pre-approval is still not the same thing as final mortgage approval.
That distinction is critical.
Mortgage Pre-Approval vs. Pre-Qualification: The Biggest Differences
The simplest way to think about the difference is:
Pre-qualification helps you understand your potential buying power.
Pre-approval helps demonstrate that a lender has taken a closer look at your ability to obtain financing.
Here are some of the biggest differences.
1. Financial Verification
A pre-qualification may rely heavily on information you provide.
A pre-approval generally involves greater documentation and verification.
That doesn’t mean every pre-approval is identical. Some lenders conduct a more extensive review than others.
2. Strength of Your Offer
A pre-approval generally gives a seller more confidence than a basic pre-qualification because it indicates that a lender has already reviewed more of your financial picture.
Freddie Mac specifically says a pre-approval can strengthen an offer and help a buyer stand out from other homebuyers.
3. Speed When You Find the Right Home
If you wait until after you find a home to begin the mortgage qualification process, you may be scrambling to provide documentation while negotiating with the seller.
Getting organized ahead of time can make the process much smoother.
The CFPB recommends getting pre-approved before you are ready to make an offer so you can better understand your financing options and demonstrate that you are a serious buyer.
4. Understanding Your Real Budget
One of the biggest benefits of getting pre-approved isn’t actually impressing the seller.
It’s knowing what you can realistically afford.
A lender can help you look beyond the purchase price and consider factors such as:
- Principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- HOA dues
- Down payment
- Closing costs
- Other monthly debts
Remember: the maximum amount a lender says you can borrow isn’t necessarily the amount you should spend.
Freddie Mac specifically cautions that the amount shown on a pre-approval is a maximum and not necessarily the amount a buyer should borrow.
Which Carries More Weight: Pre-Approval or Pre-Qualification?
In most situations, pre-approval carries more weight than a basic pre-qualification, particularly when you are submitting an offer.
InterWest Mortgage has previously explained that pre-approvals carry more weight than pre-qualifications when writing offers.
But here’s the part many homebuyers miss:
The Process Behind the Letter Matters More Than the Label
A buyer should not simply ask:
“Is this a pre-approval?”
A better question is:
“What information did you verify before issuing the letter?”
The CFPB specifically advises consumers to ask lenders what assumptions were made in issuing a pre-approval and whether anything about their financial situation could cause the loan to be denied later or change the loan’s costs.
That’s excellent advice.
Two lenders could use the term “pre-approval” while conducting reviews at somewhat different levels.
For this reason, don’t choose a lender simply because they promise a “pre-approval letter.” Ask what goes into their pre-approval process.
Do Sellers Prefer Pre-Approved Buyers?
Generally, yes.
From a seller’s perspective, accepting an offer isn’t simply about the purchase price. The seller wants to know:
“Is this buyer actually going to be able to close?”
A financed offer adds an additional layer of uncertainty because the buyer still needs to obtain a mortgage, and the property must meet the loan’s requirements.
A stronger pre-approval can reduce some of that uncertainty.
Research published in the Journal of Real Estate Research found that seller-required mortgage pre-approvals were associated with reduced transaction risk and faster closing in the studied transactions.
The National Association of REALTORS® also identifies pre-qualified and, preferably, pre-approved buyers as being in a stronger position to obtain mortgage financing promptly.
That doesn’t mean a seller will automatically choose a pre-approved buyer.
There are other factors.
What Matters in a Competitive Home Offer?
When sellers receive multiple offers, they may look at much more than the purchase price.
The National Association of REALTORS® notes that factors such as financial terms, contingencies, closing timeline, and earnest money can affect how attractive an offer is. The strongest offer isn’t necessarily the one with the highest price.
For example, imagine two buyers submit:
Buyer A
- $450,000 offer
- Pre-qualified
- Financing contingency
- 45-day closing
Buyer B
- $445,000 offer
- Strong pre-approval
- Solid financing profile
- 30-day closing
Which offer wins?
There is no universal answer.
The seller may prefer Buyer B because the seller believes the transaction is more likely to close smoothly.
This is why pre-approval can be particularly valuable in a competitive market.
Can Pre-Approval Help You Win a Bidding War?
Yes—but it doesn’t guarantee that you’ll win.
A pre-approval can make your offer more competitive because it gives the seller greater confidence that you have already taken meaningful steps toward obtaining financing.
Freddie Mac says a pre-approval can help buyers stand out and strengthen an offer.
But don’t confuse being pre-approved with having the strongest offer.
A seller may still choose another buyer because that buyer:
- Offered more money
- Has a larger down payment
- Has fewer contingencies
- Can close sooner
- Has stronger financial reserves
- Offered more favorable terms
- Is paying cash
The goal isn’t simply to obtain a pre-approval.
The goal is to build the strongest overall offer you can comfortably afford.
7 Common Mortgage Pre-Approval Mistakes Homebuyers Make
Understanding the difference between pre-qualification and pre-approval is important, but there are several other misconceptions that can cause problems.
Mistake #1: Assuming Pre-Approval Means the Loan Is Guaranteed
It doesn’t.
A pre-approval is an important step, but it is not a guarantee that the mortgage will ultimately close.
The property still needs to satisfy applicable requirements, and your financial circumstances may need to be verified again. The appraisal and other aspects of the transaction can also affect the final loan decision.
Mistake #2: Shopping for Homes Before Knowing Your Budget
It’s easy to fall in love with a house before knowing what your mortgage payment might look like.
Getting pre-approved first can help establish a realistic price range.
Mistake #3: Assuming the Maximum Loan Amount Is Your Target Price
If a lender says you could potentially qualify for $500,000, that doesn’t mean you should buy a $500,000 home.
Your personal budget, lifestyle, savings goals, and comfort level matter.
Mistake #4: Making Major Financial Changes After Pre-Approval
Once you’ve been pre-approved, don’t assume the process is finished.
Changing jobs, taking on significant new debt, making large purchases, moving money between accounts without documentation, or making other substantial financial changes can create complications.
Talk to your lender before making major financial decisions during the homebuying process.
Mistake #5: Choosing a Lender Based Only on the Interest Rate
The lowest advertised rate isn’t necessarily the best overall mortgage.
Consider the complete picture, including:
- Interest rate
- APR
- Closing costs
- Loan terms
- Available programs
- Service
- Communication
- Experience with your type of transaction
- Ability to close on time
The CFPB recommends comparing multiple mortgage offers rather than automatically choosing the first lender you speak with.
Mistake #6: Assuming Every Pre-Approval Is the Same
As discussed earlier, the CFPB specifically warns that lenders use the terms pre-qualification and pre-approval differently.
Ask what the lender actually reviewed.
Mistake #7: Thinking You Must Use the Lender Who Pre-Approved You
A pre-approval doesn’t necessarily lock you into using that lender.
The CFPB notes that getting pre-approved can help you compare lenders and financing options before selecting the mortgage you ultimately use.
How InterWest Mortgage Can Help You From Pre-Approval to Closing
Getting a mortgage pre-approval isn’t just about obtaining a letter.
It’s about understanding your options before you make one of the largest financial decisions of your life.
That’s where working with an experienced mortgage team can make a difference.
At InterWest Mortgage, the process begins with helping you understand your financial position, potential loan options, estimated payments, and buying power.
From there, the team can help you prepare for the home search and move into the financing process once you have an accepted offer.
InterWest Mortgage has served homebuyers in Idaho and all 50 states since 1986 and handles major portions of the mortgage process in-house, including processing, underwriting, closing, and funding. The company says this approach is designed to improve communication, efficiency, and control throughout the transaction.
That can be especially valuable when you’re competing for a home and timing matters.
InterWest also offers pre-qualification and application options with its mortgage professionals, including Joni Kepler, Jason Speirs, and Sean Finch.
The company’s current website reports more than 500 customer reviews and emphasizes personalized service and a stress-free home loan experience.
Step 1: Start With a Conversation
Before looking at homes, talk with a mortgage professional.
Discuss your income, debts, savings, credit, down payment, goals, and timeline.
This gives you an opportunity to identify potential issues before you are under contract.
Step 2: Get Pre-Approved
Once you’re ready to shop seriously, work toward a documented pre-approval.
This can give you a clearer understanding of your borrowing power and provide a stronger financing story when you submit an offer.
Step 3: Shop With Confidence
With your financing strategy established, you can search for homes that fit your budget instead of guessing what you can afford.
Step 4: Build a Strong Offer
When you find the right home, your real estate agent and mortgage professional can work together to help structure an offer that makes sense for your financial situation and the seller’s circumstances.
Step 5: Keep Your Lender Updated
After your offer is accepted, the process isn’t over.
Continue communicating with your lender and promptly provide requested documentation. Your lender can help keep the loan moving through processing, underwriting, appraisal, and closing.
The Bottom Line: Pre-Approval Is Usually the Better Choice When You’re Ready to Buy
If you’re just starting to think about buying a home, pre-qualification can be a helpful first step for understanding your potential price range.
But if you’re ready to start seriously shopping and expect to make an offer, a strong mortgage pre-approval is generally the better position to be in.
It can help you:
- Understand your realistic buying power
- Identify financial issues early
- Shop within an appropriate price range
- Demonstrate that you’re a serious buyer
- Strengthen your offer
- Compete more effectively against other buyers
- Move more efficiently once you have a contract
Most importantly, remember that the strength of a pre-approval depends on the lender’s process—not simply the word printed at the top of the letter.
Before you begin your home search, talk with a mortgage professional about what has been verified, what assumptions were made, how much you can comfortably afford, and what you can do to put yourself in the strongest possible position.
Ready to Get Pre-Approved?
Buying a home can feel complicated, especially when you’re trying to understand mortgage terminology, loan programs, rates, down payments, closing costs, and what sellers expect from buyers.
You don’t have to figure it all out alone.
InterWest Mortgage can help you understand your financing options, determine a realistic price range, prepare for pre-approval, and guide you through the mortgage process from your first conversation through closing.
Whether you’re a first-time homebuyer or you’ve purchased a home before, getting started with the right mortgage strategy can make the entire experience easier—and help you act quickly when the right home comes along.
Talk with InterWest Mortgage today and take the first step toward buying your next home with confidence. Give us a call today at 208-525-8778.