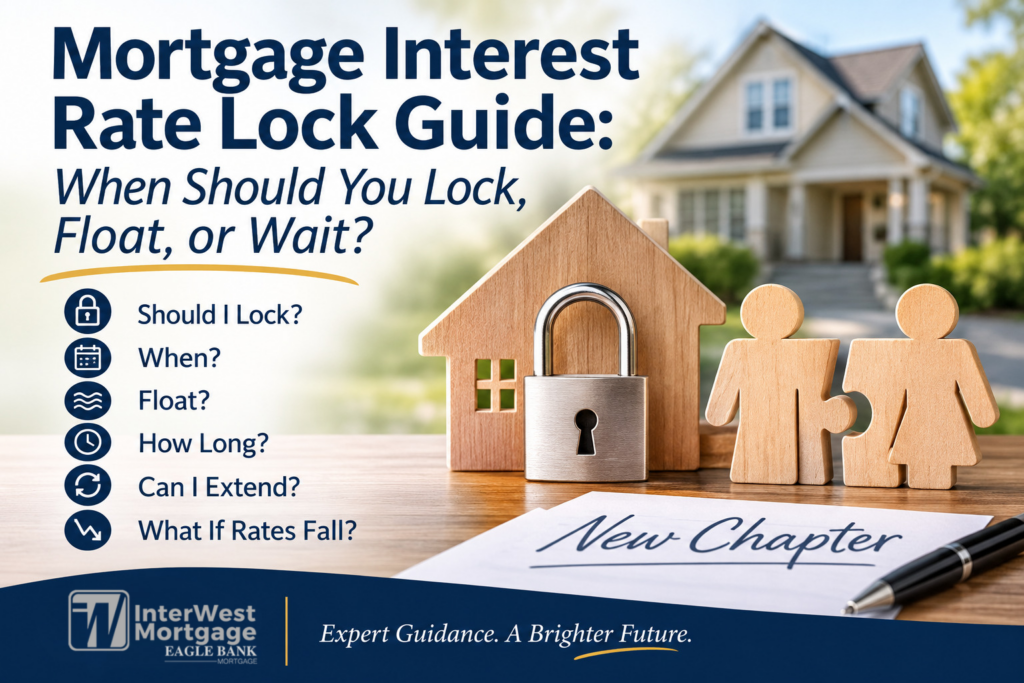
Buying a home is a major financial decision. When you’re also navigating a divorce, knowing when to lock your mortgage interest rate can make an important difference in your financial future.
Mortgage interest rates can change daily, sometimes even hourly. Locking at the right time can protect you from unexpected increases, while waiting could potentially give you an opportunity to secure a lower rate.
For individuals going through a divorce, these decisions deserve additional attention. You may be waiting for a marital home to sell, dividing assets, establishing individual income, or trying to coordinate a new home purchase with your divorce settlement.
At InterWest Mortgage, we understand that buying a home during or after a divorce involves more than simply finding a competitive interest rate. It’s about understanding your financial circumstances and making informed decisions that support your next chapter.
Here’s what you should know about mortgage rate locks and how to determine the right strategy for your situation.
What Is a Mortgage Interest Rate Lock?
A mortgage interest rate lock is an agreement with your lender to hold a specific interest rate for a designated period while your loan moves through the approval and closing process.
For example, if you lock your mortgage rate at 6.25% for 45 days, that rate generally remains unchanged even if market rates increase during that period, provided your loan closes within the lock period and your application remains eligible.
Most lenders offer 30-, 45-, or 60-day locks, although longer periods may be available.
A rate lock protects against rising rates, but it doesn’t guarantee final loan approval or protect against every change to your loan terms.
For additional information, visit the Consumer Financial Protection Bureau’s (CFPB) official mortgage rate lock guide.
1. Should I Lock My Mortgage Interest Rate?
For many homebuyers, locking makes sense once they’ve found a property, negotiated an accepted offer, and are comfortable with the quoted interest rate and monthly payment.
Consider locking if:
- You can comfortably afford the payment at the quoted rate.
- You have an accepted purchase agreement.
- Your closing date is approaching.
- You want protection against potential rate increases.
- Your financial circumstances and down payment are reasonably established.
Why this matters in divorce: Your financial situation may already be uncertain. If you’ve determined what you can afford and found a home that meets your needs, protecting your mortgage rate can provide some financial predictability while other aspects of your divorce are being finalized.
However, don’t lock simply because you fear rates might increase tomorrow. Discuss your options and closing timeline with your mortgage professional first.
2. When Should I Lock My Mortgage Rate?
Generally, a good time to consider locking is after your purchase agreement is accepted and your lender has enough information to establish your loan structure and expected closing date.
Locking too early could mean your lock expires before closing. Waiting too long exposes you to potential rate increases.
Divorce can complicate this timing. Perhaps you’re waiting for proceeds from selling your marital home, finalizing your settlement, or documenting your new financial obligations.
Before locking, make sure your lender understands:
- Your expected income after divorce.
- Any alimony or child support payments.
- Existing mortgage and jointly held debts.
- Your expected down payment and asset distribution.
- Whether your divorce decree or settlement is finalized.
Your rate lock should fit your actual financial and closing timeline.
3. Should I Float My Mortgage Rate Instead?
Floating means choosing not to lock your rate immediately. Your mortgage rate remains subject to market fluctuations until you decide to lock in.
If rates fall, you could potentially secure a lower rate. If they rise, you could end up paying more.
Floating might make sense if your closing is several months away, you’re still evaluating properties, or your loan structure hasn’t been finalized.
However, mortgage rates are influenced by inflation, employment reports, bond markets, and broader economic conditions. Even experienced mortgage professionals cannot consistently predict their direction.
Our recommendation: Don’t make your decision based on market speculation alone. Consider your budget, closing timeline, and tolerance for risk. If you already have an affordable payment plan, the security of locking in may outweigh the potential to save a little more by waiting.
4. How Long Does a Mortgage Rate Lock Last?
Common mortgage rate lock periods include:
| Lock Period | Typical Situation |
| 30 days | Faster closings |
| 45 days | Typical home purchases |
| 60 days | Transactions needing additional time |
| 90+ days | Extended closings or certain new construction purchases |
Longer locks may involve different interest rates, points, or additional costs.
During divorce, a longer lock may be worth considering if your transaction requires additional documentation, a marital home sale, or coordination with a divorce settlement.
Ask your loan officer to compare the cost of different lock periods before making a decision.
5. Can I Extend My Mortgage Rate Lock?
Yes. Many lenders offer extensions if your loan isn’t ready to close before the original lock expires.
However, extensions may involve additional fees.
Divorce-related delays can include waiting for a signed decree, resolving property division, completing the sale of a marital home, or documenting support payments and financial obligations.
To avoid unnecessary expenses, ask your lender:
- What happens if my closing is delayed?
- How much does an extension cost?
- Can I initially choose a longer lock?
- When should I request an extension?
Don’t wait until your rate lock is about to expire to discuss your options.
6. What If Mortgage Rates Fall After I Lock?
This is one of the biggest concerns borrowers have.
Suppose you lock your rate at 6.25%, but two weeks later market rates fall to 5.99%.
Generally, your original locked rate remains in place. However, some lenders offer a float-down option, which may allow you to take advantage of improved market pricing before closing.
Float-down provisions vary. Some require rates to improve by a minimum amount, and additional fees or restrictions may apply.
Before locking, ask your loan officer:
“If mortgage rates drop after I lock, will I have an opportunity to take advantage of the lower rate?”
Understanding your options beforehand can prevent surprises later.
7. Can My Divorce Settlement Affect My Mortgage After Locking?
Absolutely. A rate lock doesn’t guarantee that your original mortgage approval will remain unchanged if your financial circumstances change.
For example, your divorce settlement might establish new alimony payments, change your debt responsibilities, or alter your available down payment.
These changes could affect your debt-to-income ratio, qualifying income, or loan approval.
Fannie Mae has specific documentation requirements for sources of income, such as alimony and child support. Depending on the circumstances, lenders may require a divorce decree or separation agreement, evidence of payment history, and documentation that the income will continue.
If you’re buying a home during a divorce, keep your mortgage professional informed of any changes to your settlement, income, assets, or debts.
Review Fannie Mae’s current Selling Guide for income and debt documentation requirements.
8. Why Work With InterWest Mortgage?
Buying a home during or after divorce is an important financial transition. You need more than an interest rate quote. You need a mortgage team that understands your circumstances and can help you evaluate your options.
With 43 years of mortgage lending experience, more than 550 five-star reviews, and recognition as a 2026 Best of Greater Idaho Falls Gold Winner, InterWest Mortgage has built a reputation for helping individuals and families navigate home financing.
InterWest offers a variety of mortgage solutions, including:
- Conventional Loans: Flexible financing for qualified borrowers.
- FHA Loans: Options with more flexible qualification requirements for eligible buyers.
- VA Loans: Financing for eligible veterans and qualifying service members.
- First-Time Homebuyer Loans: Guidance for individuals purchasing their first home.
- Refinancing: Options for evaluating existing mortgage financing.
- New Construction Loans: Financing guidance for building a home.
Whether you’re purchasing a new home, refinancing the marital property, or establishing financial independence after divorce, InterWest’s mortgage professionals can help you understand your possibilities.
Frequently Asked Questions
Should I lock my mortgage rate or float?
Locking protects against rising rates. Floating provides an opportunity to benefit if rates fall but carries the risk of increases.
How long should I lock my mortgage rate?
Most borrowers consider 30-, 45-, or 60-day locks. Choose a period that reasonably covers your expected closing timeline.
Can I extend an expired mortgage rate lock?
Often, yes. However, extensions may involve additional costs and depend on lender policies.
Can I get a lower rate after locking?
Possibly. Ask whether your lender offers a float-down or repricing option.
Can I qualify for a mortgage before my divorce is final?
Potentially. Qualification depends on your income, debts, assets, documentation, and the specific loan program. You don’t necessarily have to wait until your divorce is finalized to explore mortgage options.
Make Your Next Home a Fresh Start
Choosing when to lock your mortgage interest rate is an important decision. When you’re navigating divorce, the decision deserves even more attention.
Your income, financial obligations, settlement agreements, and closing timeline can all influence your mortgage options.
The best approach is to understand your choices and work with a mortgage professional who takes the time to understand your situation.
Your next home represents a new chapter. Make sure your mortgage helps you build the financial foundation you want for that chapter.
Ready to explore your options? Contact InterWest Mortgage today. Their experienced team can help you evaluate your financing possibilities and take the next step toward homeownership.
Explore Your Mortgage Options With InterWest Mortgage
Click: SEE WHAT YOU QUALIFY FOR to get started.
This article provides general educational information. Mortgage rates, lock periods, fees, and underwriting requirements vary by lender and loan program. Consult your mortgage professional regarding your individual circumstances.