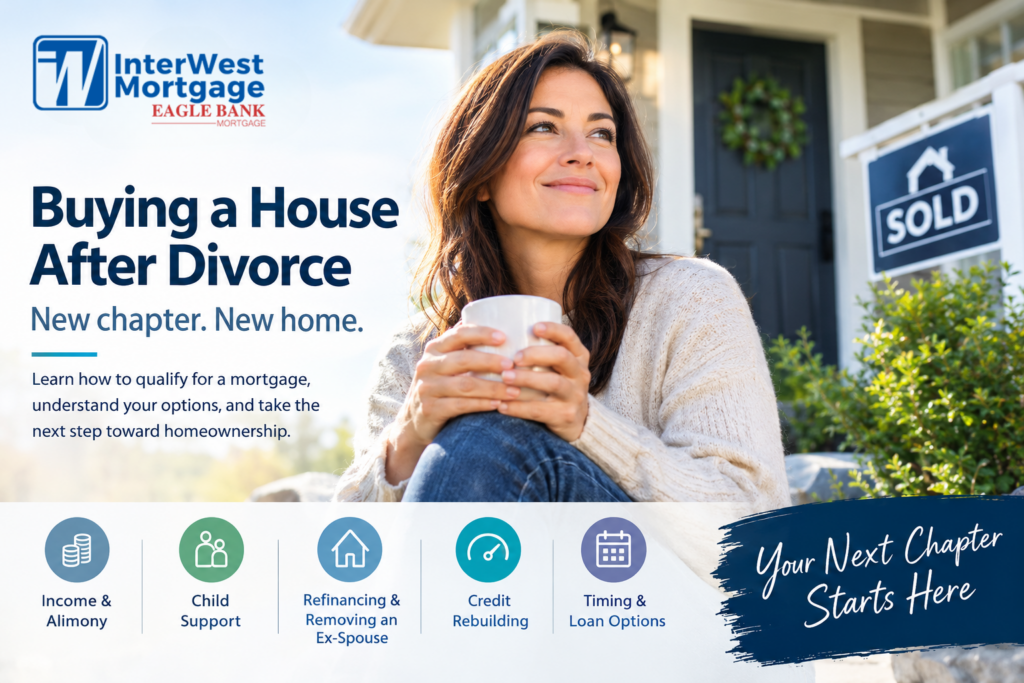
Divorce can change nearly every part of your financial life, including where you live, how you manage your money, and what you can afford. If you’re thinking about buying a house after a divorce, you may be wondering whether you can qualify for a mortgage on a single income, how alimony or child support affects your application, or whether you need to wait until your divorce is finalized.
The good news is that buying a house after divorce is possible, and you may have more mortgage options than you realize. The key is understanding how lenders evaluate your finances, preparing the right documentation, and choosing a home loan that fits your new circumstances.
At InterWest Mortgage, our experienced mortgage team helps homebuyers navigate important financial decisions with personalized guidance and a range of home loan options. Whether you’re purchasing your first home on your own, refinancing a property you shared with your former spouse, or rebuilding your financial foundation, understanding your options is an important first step.
Can You Buy a House After Divorce?
Yes. You do not necessarily have to wait until you’ve been divorced for a certain number of years to buy a house. Depending on your circumstances, you may qualify for a mortgage before or after your divorce is finalized.
Lenders generally evaluate your ability to repay the loan by reviewing factors such as:
- Your current income and employment history
- Your credit score and credit history
- Your existing debts and monthly obligations
- Your down payment and available assets
- Your debt-to-income ratio
- Any alimony or child support payments you receive or make
Your divorce settlement can also affect your mortgage application, particularly if it changes your income, debt obligations, or ownership of an existing home.
Rather than assuming you must wait, consider speaking with a mortgage professional early. An experienced loan officer can help you understand where you stand today and identify steps that could improve your eligibility.
1. Understanding Income When Buying a House After Divorce
One of the biggest financial adjustments after divorce is learning to manage household expenses on a different income.
If you previously shared a mortgage, utilities, insurance, and other living expenses with your spouse, qualifying for a new home loan may require a fresh look at your budget.
Mortgage lenders typically consider income that is documented, stable, and likely to continue. Depending on your situation, qualifying income may include:
- Salary or hourly wages
- Self-employment income
- Eligible retirement or disability income
- Qualifying alimony or child support
- Other income sources permitted by the applicable loan program
Your income is only one part of the equation. Lenders also consider your monthly debts, including car payments, credit card payments, student loans, and any applicable support obligations.
Practical tip: Before shopping for a home, determine what monthly payment comfortably fits your new budget. Include property taxes, homeowners insurance, utilities, maintenance, and any homeowners association fees—not just the mortgage payment.
InterWest Mortgage can help you explore available loan options and understand how your current financial situation may affect your purchasing power.
2. Can You Use Alimony or Child Support to Qualify for a Mortgage?
Alimony and child support can make a meaningful difference when you’re applying for a mortgage after divorce. Depending on the loan program and your documentation, eligible payments you receive may count toward qualifying income.
However, lenders must follow specific requirements regarding payment history, documentation, and the expected continuation of that income. For example, Fannie Mae’s conventional mortgage guidelines generally require documentation of the payment terms, a history of regular receipts, and evidence that qualifying payments are expected to continue for at least three years. Other loan programs may have different requirements.
Source: Fannie Mae’s guidelines for alimony and child support income.
If you receive alimony or child support
Be prepared to provide documents such as:
- Your divorce decree or legally binding separation agreement
- Documentation showing the required payment amounts and duration
- Bank statements or other records demonstrating receipt of payments
If these payments are essential to qualifying for your mortgage, the lender will need to determine whether they meet the applicable program requirements.
If you pay alimony or child support
Support payments may affect how much you can borrow by reducing the income available for other monthly obligations.
Your loan officer will review your circumstances and determine how the payments should be treated under the applicable mortgage guidelines.
Important: Never assume that every dollar of support received will automatically count as qualifying income or that every support obligation will be treated identically by every lender. Discuss the details of your agreement with your mortgage professional before making a purchasing decision.
3. Refinancing a Home After Divorce
If you and your former spouse own a home together, deciding what happens to the mortgage is often one of the most important financial questions in your divorce.
You may decide to sell the home, keep it jointly for a period of time, or have one spouse remain in the property.
If one spouse wants to keep the home and take over the financing, refinancing may be an option.
A refinance replaces the existing mortgage with a new loan. The spouse keeping the home must generally qualify for the new mortgage based on their own financial circumstances, and the transaction may involve closing costs and a different interest rate.
Before refinancing, consider:
- Whether your income is sufficient to support the new payment
- How much equity is in the property
- Whether you need to compensate your former spouse for their share of the equity
- Whether the new interest rate and loan terms are financially reasonable
- Whether you have enough funds for closing costs and other expenses
If your existing mortgage has a favorable interest rate, refinancing could be expensive. Depending on the loan and circumstances, an assumption or another servicer-approved option may be available instead.
The right choice depends on your existing mortgage, the terms of your divorce, and your financial goals.
4. How to Remove an Ex-Spouse From a Mortgage
One common misconception is that removing a former spouse’s name from a home’s title automatically removes them from the mortgage.
It does not. Property ownership and responsibility for a mortgage are separate issues.
A divorce decree may award the home to one spouse, but that does not automatically release the other spouse from their contractual responsibility for the mortgage.
Depending on the loan, possible options may include:
- Refinancing: Replacing the current mortgage with a new loan in the remaining homeowner’s name.
- Mortgage assumption: Taking over an eligible existing mortgage, subject to the loan’s requirements and servicer approval.
- Release of liability: Requesting that the mortgage servicer formally release the departing borrower when permitted.
Fannie Mae explains that certain transfers following divorce may have refinancing alternatives, but eligibility and the process depend on the specific mortgage. An assumption does not automatically release the original borrower from liability.
Source: Fannie Mae’s guide to changing or transferring homeownership.
If you’re keeping your home after a divorce, contact your mortgage servicer and a qualified mortgage professional to understand your options. If you are buying a different home, make sure you understand how any continuing responsibility for your former mortgage could affect your new application.
5. Rebuilding Your Credit After Divorce
Divorce does not automatically damage your credit score. However, changes in household finances, missed payments, increased credit card balances, and joint debts can affect your credit over time.
If your credit needs improvement before you apply for a mortgage, a few practical steps can help.
Review your credit reports
Check your credit reports for errors, unfamiliar accounts, and debts that may still be associated with you and your former spouse.
Make payments on time
Your payment history is an important part of your credit profile. Prioritize making all required payments by their due dates.
Reduce revolving debt
Lower credit card balances when possible. Reducing revolving debt can improve your credit utilization and may also help your debt-to-income ratio.
Avoid unnecessary new debt
Large purchases or new credit accounts immediately before applying for a mortgage may complicate your application.
Keep track of joint obligations
Even if your divorce agreement assigns a debt to your former spouse, creditors may still hold you responsible under the original account agreement. Confirm that payments are being made and seek professional guidance if problems arise.
You may not need perfect credit to buy a home. Different mortgage programs have different eligibility standards, so ask your loan officer which options may fit your situation.
6. When Is the Best Time to Buy a House After Divorce?
There is no universal waiting period for buying a home after divorce. The right timing depends on your financial readiness, housing needs, and the details of your situation.
Before making an offer, consider these important milestones:
Your income is clear. You understand what you earn and which support payments, if any, can be included in your mortgage application.
Your debts are accounted for. You know which obligations remain in your name and how they affect your monthly budget.
Your divorce-related finances are documented. You have the necessary agreements, payment records, and information about any property settlement.
You have funds available. You have evaluated your down payment, closing costs, and a reasonable emergency reserve.
You understand your mortgage options. You have discussed loan programs, credit requirements, and potential monthly payments with a mortgage professional.
If your divorce is still in progress, you may be able to begin exploring financing before everything is finalized. However, changes to support obligations, property awards, or debts can affect your eligibility, so coordinate with your attorney and loan officer before committing to a purchase.
In some cases, waiting a few months to stabilize your finances or rebuild your credit can put you in a stronger position. In others, moving forward sooner may make sense.
The goal is not simply to buy a house as quickly as possible. It is to make a decision that supports your long-term financial stability.
7. Which Mortgage Programs Should You Explore After Divorce?
The right loan program depends on your credit, income, down payment, location, and eligibility.
InterWest Mortgage offers several types of home financing that may be worth exploring.
- Conventional loans: May be suitable for borrowers who meet the program’s credit, income, and down payment requirements.
- FHA loans: May offer flexible qualifying criteria and lower down payment options for eligible borrowers.
- VA loans: Eligible veterans and service members may qualify for benefits, including no-down-payment financing.
- USDA Rural Development loans: Eligible properties and borrowers may qualify for financing with no down payment.
- Idaho Housing assistance programs: Depending on your location and eligibility, assistance may be available for down payments or closing costs.
Availability and requirements vary by program, property, and borrower. Your loan officer can help you compare the options and determine which ones warrant further consideration.
Why Work With InterWest Mortgage?
When you’re buying a house after divorce, you deserve clear answers and a mortgage team that understands the importance of getting the details right.
InterWest Mortgage has served homebuyers in Idaho and surrounding markets for decades. Its team includes experienced mortgage professionals such as Joni Kepler, Jason Speirs, and Sean Finch, who help borrowers explore financing options suited to their needs.
InterWest also emphasizes no upfront fees, in-house processing, underwriting, closing, and funding, allowing its team to coordinate important steps throughout the mortgage process.
Whether you’re purchasing a home for the first time on your own, refinancing a property after divorce, or preparing to qualify for a mortgage with a changed financial situation, InterWest Mortgage can help you understand the process and evaluate your options.
Learn more about the team by clicking here.
Start Your Next Chapter With a Clear Plan
Buying a house after divorce can feel overwhelming, especially when you’re adjusting to a new budget, sorting through financial obligations, and deciding where to live next.
But you don’t have to figure everything out at once.
Start by understanding your income, reviewing your credit, organizing your divorce-related financial documents, and exploring your mortgage options. With the right preparation and guidance, you can make informed decisions about your next home.
Ready to find out whether you qualify for a mortgage after divorce? Contact InterWest Mortgage to discuss your circumstances, explore available home loan programs, and take the next step toward homeownership.
Email us or call (208) 525-8778 to see how InterWest can help your specific situation.
This article is for educational purposes only and is not legal, tax, or individualized financial advice. Mortgage approval, qualifying income, loan terms, and program eligibility depend on underwriting requirements and your individual circumstances. Consult your attorney regarding divorce agreements and your mortgage servicer regarding existing loan obligations